
Dealerships in focus
GROUP PERFORMANCE


Operating environment
Dealerships SA and Dealerships UK operate in the areas mentioned below.
Dealerships SA: Gauteng, North West, Mpumalanga and Western Cape Provinces.
Dealerships UK: Coventry, Rugby, Nuneaton, Warwick, Solihull, Riverside, Daventry, Kettering, Northampton, Romford, Brentwood, Warley, Upminster, Basildon, Swindon, Bath, Rayleigh, Southend, Lakeside, Slough, Uxbridge, Gravesend, Sittingbourne and Crayford.
DEALERSHIPS SA
Strategy
Dealerships SA’s strategy is to be a highly efficient and dynamic dealerships business representing multiple OEMs across South Africa.

Graeme Watson (53)
Chief Executive Officer Dealerships
| Material risks | Mitigating factors |
|
|
|
|
|
|
|
|
| Opportunities | |
| Ownership of strategic properties | Significant advantages can be derived through strategic property ownership by reducing lease cost averaging and avoiding substantial rental escalations. |
| “Going Above and Beyond” | Dealerships’ culture remains fundamental to improved morale, staff retention, and ultimately resulting in improved customer service and retention. |
| Finance and Insurance income | The division continues to improve its product offering and service levels. Continuously enhanced customer value will enable these income streams to be maintained. |
| Multi-franchising | Selected OEMs are allowing multi-franchising in certain areas, and Dealerships SA has a number of these arrangements in place as it reduces overhead costs and enhances property efficiencies. |
| Digital market place | Increased focus on the digital marketing environments will provide increased sales opportunities to the division and to enhance transaction capability in collaboration with the financial institutions. The digital platform will improve the on-line customer experience. |
Activities
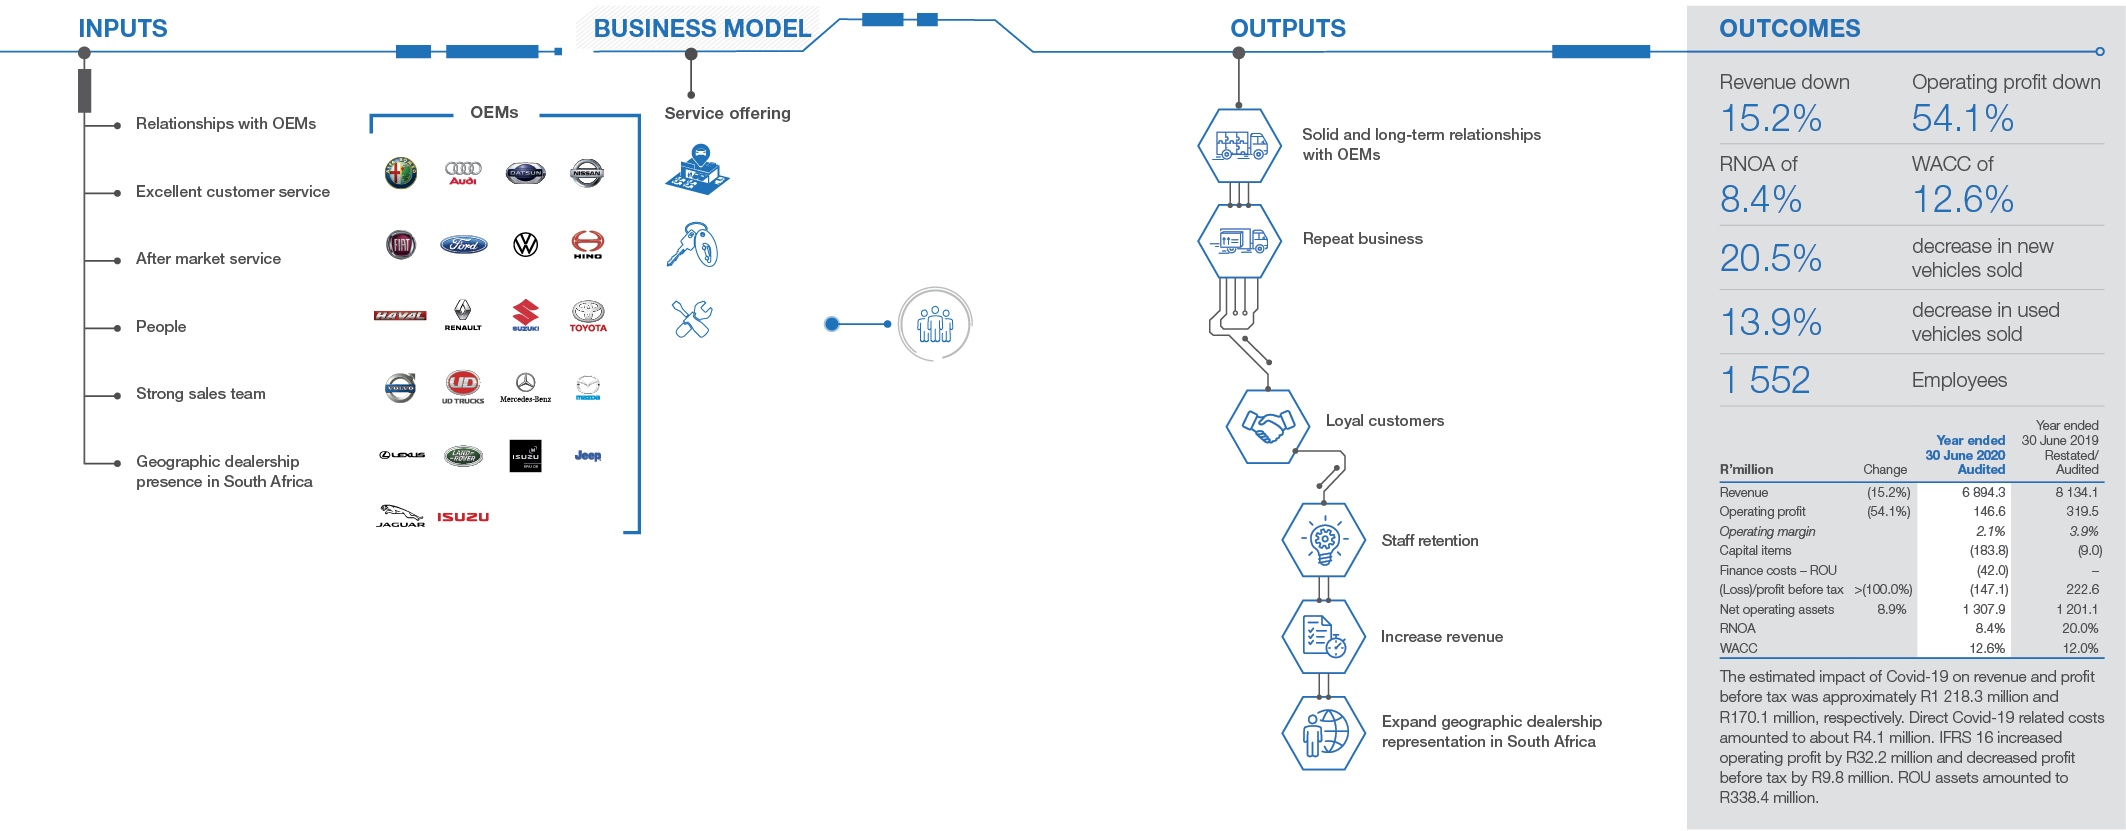
As at 30 June 2020, the Dealerships business consisted of 44 (June 2019: 48) franchised motor dealerships, made up of 38 (June 2019: 39) passenger vehicle and six (June 2019: eight) commercial vehicle dealerships, based in the Gauteng, North West, Mpumalanga and Western Cape Provinces. The Super Group Pre-Owned dealership concept was closed during the year.
The division represents the majority of major brands including Nissan, Renault, Ford, Mazda, Toyota, Lexus, Mercedes-Benz (including SMART), Land Rover, Jaguar, Volvo, Jeep, Datsun, Volkswagen, Audi, Isuzu, Haval, GWM, Suzuki, Alfa Romeo, Fiat (including Abarth), UD trucks, Hino trucks, FUSO trucks Mercedes-Benz trucks and Isuzu trucks. The majority of new vehicle sales are passenger and light commercial vehicles, while medium, heavy and extra heavy commercial vehicles represent slightly more than 7.7% (June 2019: 6%) of new vehicle sales.
Results for 2020
Dealerships SA reported sales volumes that mirrored the NAAMSA sales trends and market statistics prior to the Covid-19 lockdown, with the premium luxury segment reporting the largest volume declines. The implementation of the hard lockdown forced all dealerships throughout the country to shut their doors for 40 days, and only support for essential service personnel was permitted. The South African motor industry did not operate during April, was at minimal capacity in May, and only resumed full operation in June. Dealerships were permitted to commence with general servicing from the 6 May 2020 and sales commenced in the latter part of May. Demand levels in June 2020 were remarkably strong by comparison as pent-up demand for vehicles, parts and service drove robust activity levels.
Dealerships SA closed four dealerships during the year under review. The division developed a new facility in Cape Town, enabling the consolidation of two of its Western Cape commercial vehicle dealerships.
New vehicle sales volumes (excluding the closed dealerships) declined by 20.5% (2019: 1.5%) and mirrored the NAAMSA dealer market decline for the financial year ended 30 June 2020. Similarly, used vehicle sales volumes (excluding the closed dealerships) were also heavily affected by the Covid-19 lockdown and declined by 13.9% (2019: 8.9%), which is a trend that was also evident in the Parts and Service business.
The estimated impact of Covid-19 on revenue and profit before tax was approximately R1 218.3 million and R170.1 million, respectively. Direct Covid-19 related costs amounted to about R4.1 million. IFRS 16 increased operating profit by R32.2 million and decreased profit before tax by R9.8 million.
A total impairment against goodwill of R171.0 million was made, mainly against the Western Cape Mercedes-Benz dealerships of R155 million. Property to the value of R12.6 million was also impaired.

Environment, sustainability and governance
Refer to the ESG Report.

Outlook for 2021
The Dealerships SA business is anticipating difficult trading conditions for the year ahead as consumers remain under severe pressure, despite the three interest rate cuts announced by the South African Reserve Bank. The repo rate at 3.5% and the prime commercial lending rate at 7.0%, are record lows last seen 40-years ago. The significant decline in the new and used sales during the lockdown period is expected to recover gradually over the course of the coming year. This is not however, expected to reach pre-Covid sales levels in the medium-term. The resultant low economic growth and business confidence in South Africa, as well as the increase in unemployment rates, are expected to compound the already challenging recovery process.
The focus for Dealerships SA will be a shift towards resilience, recovery, and creating a strategy to deal with new consumer behaviour. With the outbreak of Covid-19, the emphasis on operating an efficient and effective online platform for the buying and selling of new and used vehicles has been pushed to the top of the Dealerships SA’s priority list. This, together with right-sizing the dealership footprint and staff resources, as well as an uncompromising approach to cost containment, will be critical to ensure that this division successfully mitigates the Covid-19 fall-out.
Dealerships SA does however enter this process with a strong and stable management team that will directly implement and oversee the Covid-19 recovery plans and is well positioned to deal with the numerous challenges and ever changing environment that it currently faces.
DEALERSHIPS UK
Strategy
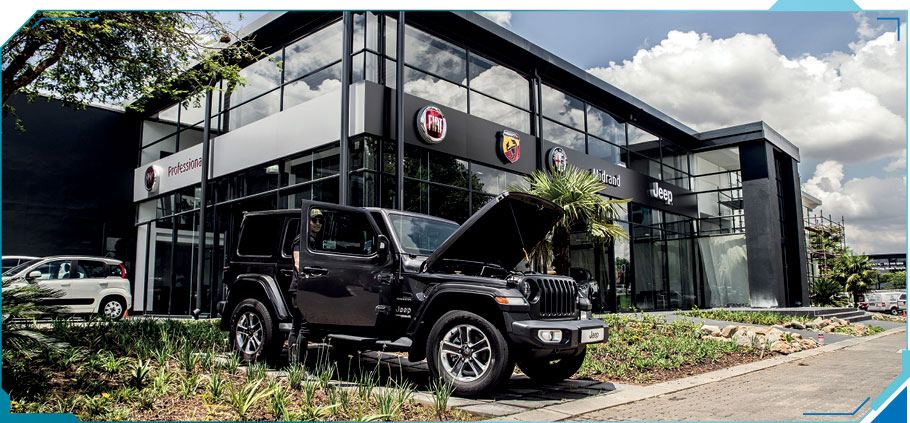
Dealerships UK’s strategy is to be the leading Ford dealership group in the UK.
Graeme Watson (53)
Chief Executive Officer Dealerships
Niall Hooper (51)
Chief Executive Officer Dealerships UK
| Material risks | Mitigating factors |
|
|
|
|
|
|
|
|
| Opportunities | |
| New vehicle sales |
Ford continues to be the market leader in the UK and Dealerships UK has a strong Ford presence with flagship dealerships in key locations. KIA is one of the most desirable franchises in the UK. Our relationships with KIA are strong and we have been granted an additional territory. |
| Fleet and commercial |
Demand for commercial vehicles continues to be robust and is likely to increase if an orderly Brexit is achieved. Our dealerships are geographically well positioned to take advantage of this segment and potential opportunity. |
| Used vehicle sales | Online enquiries for used vehicles is ever increasing and our new website will enable the business to take advantage of this opportunity. |
| Service and parts | A growing ageing vehicle car parc with the customers keeping their vehicles for longer periods is expected to result in a greater opportunity for vehicle servicing, repairs and parts sales. |
| Ownership of strategic properties and consolidation of portfolio |
Availability of properties in the UK is limited and relocation at the end of a lease is often challenging and costly. Significant cost and certainty of tenure advantages can be derived through the ownership of strategic properties, which also mitigates an extremely landlord friendly environment. |

Activities
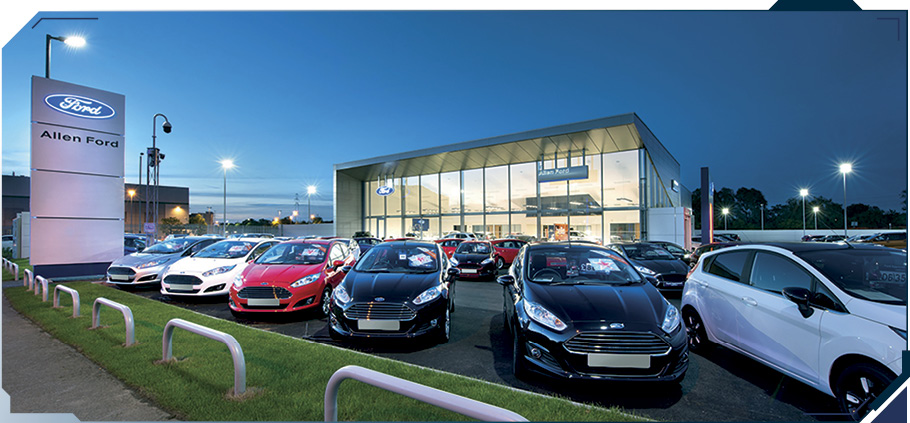
Allen Motor Group comprises 28 franchised motor dealerships in key franchise and retail areas in England. It operates the second largest independently-owned Ford franchise network in the UK, with 23 (June 2019: 24) franchised Ford motor dealerships, four (June 2019: four) franchised Kia dealerships, with a fifth due to open in early 2021, and one Mazda Dealership.
This includes Ford dealerships in Coventry, Rugby, Nuneaton and Warwick and a Kia dealership in Solihull in the Midlands. In Northampton County, Allen Motor Group has four Ford dealerships in Northampton, Daventry, Kettering and Bedford Road, with the latter being a commercial vehicle dealer. In Essex County, Allen Motor Group has seven Ford dealerships, two Kia dealerships with a third opening early 2021 together with one Mazda dealership. One of the Ford dealerships, situated in Basildon, is regarded as the largest flagship Ford Store in the UK and is immediately adjacent to the Ford UK Technical Centre where we also operate a pop-up store to serve the significant Ford employee market.
In the Swindon County, Allen Motor Group has a Ford dealership in Swindon and both a Ford and Kia dealership in Bath. The final county of representation is Kent, where Allen Motor Group operates dealerships in Crayford, Gravesend and Sittingbourne.
As one of the UK’s leading Ford dealership groups, Allen Motor Group has substantial leverage, enabling it to stock large volumes of new and used passenger and light commercial vehicles (vans), which in turn gives the group a competitive advantage in the high volume new vehicle market. The Group is also a Motability Premier Partner, which is the leading car scheme in the UK for disabled people, enabling them to use their UK Government-funded mobility allowance to lease a new car. Moreover, it is one of the UK’s largest Privilege dealers, selling a high volume of cars at preferential prices to Ford, Jaguar, Land Rover and Aston Martin employees and their families.
Results for 2020
With the outbreak of Covid-19, dealerships across the UK were closed for a period of 63 days with all OEMs closing their plants for two months. A number of franchise and industry issues existed prior to the Covid-19 lockdown, which also negatively impacted on the results. Dealerships UK reported a decline in revenue, in Pound Sterling-terms, of 25.9%, as a result of a 31% decline in new vehicle sales, a 16% decline in used vehicles sales and the impact of the lockdown on the Aftersales business.
Subdued confidence levels around Brexit, and the industry as a whole, negatively affected privilege sales volumes and market shares. This had a severe impact on the overall UK retail vehicle market, which reported a decline of 28% in volumes over the prior year. Dealerships UK’s share of Ford retail sales declined marginally to 8.35% (June 2020) from 8.91% (June 2019), while Kia increased its retail sales share from 1.73% (June 2019) to 1.97% (June 2020). The Parts and Services business was performing satisfactorily to the end of February 2020 but was severely impacted as a result of the reduced operating days caused by the lockdown. Operating profit in Pound Sterling-terms declined by 82.7%.
The estimated impact of Covid-19 on revenue and profit before tax was approximately R2 515.2 million and R245.2 million, respectively. Direct Covid-19 related costs amounted to about R17.5 million. IFRS 16 increased operating profit by R13.6 million and decreased profit before tax by R3.3 million.
Despite the tough trading conditions, the business achieved Ford’s top level of bonus target achievement in each quarter.
Environment, sustainability and governance
Refer to the ESG Report.
Outlook for 2021
The UK dealership market is expected to remain under pressure as a result of the uncertainty pertaining to the outcome of Brexit, with negotiations coming to a halt at the onset of the Covid-19 pandemic. The change in government policies on diesel technology, as well as the full impact of the pandemic on the UK economy will further challenge the business in the year ahead. Both these issues are expected to have potential effects on the OEMs supply of vehicles in certain segments.
An analysis of the existing dealership footprint, together with a critical review of overhead structures and the required staff resources, will be essential to ensure that the Group successfully recovers from the Covid-19 fall-out and is able to navigate any potential Brexit challenges.
The strong Ford and Kia presence of Dealerships UK remains key to the Group’s resilience in the current market and to the delivery of our objectives. This, together with our online digital sales strategy, driven by a strong and stable management team, will positively position the Group to deal with the challenges of a rapidly evolving market in the year ahead.
SERVICES
The Services segment includes the Corporate and the Mauritius operations. The Services segment performed well on the back of the solid performance by Treasury together with other recoveries.
The Corporate operations entail the Head Office and IT functions of the South African operations.
Super Group Commercial Trading, based in Mauritius, specialises in trade finance, commercial trading and foreign exchange management. All of Super Group South Africa’s international procurement activities are administered through this business.
The impact of Covid-19 on revenue and profit before tax was approximately R1.4 million and R0.6 million, respectively.